Cumulative vs. non-cumulative preferred stocks
One clause in the prospectus decides whether a missed dividend must be paid later or is lost. It is priced at little in normal times and matters when an issuer runs into trouble.
Manish Hemrajani9 min readPublished Updated
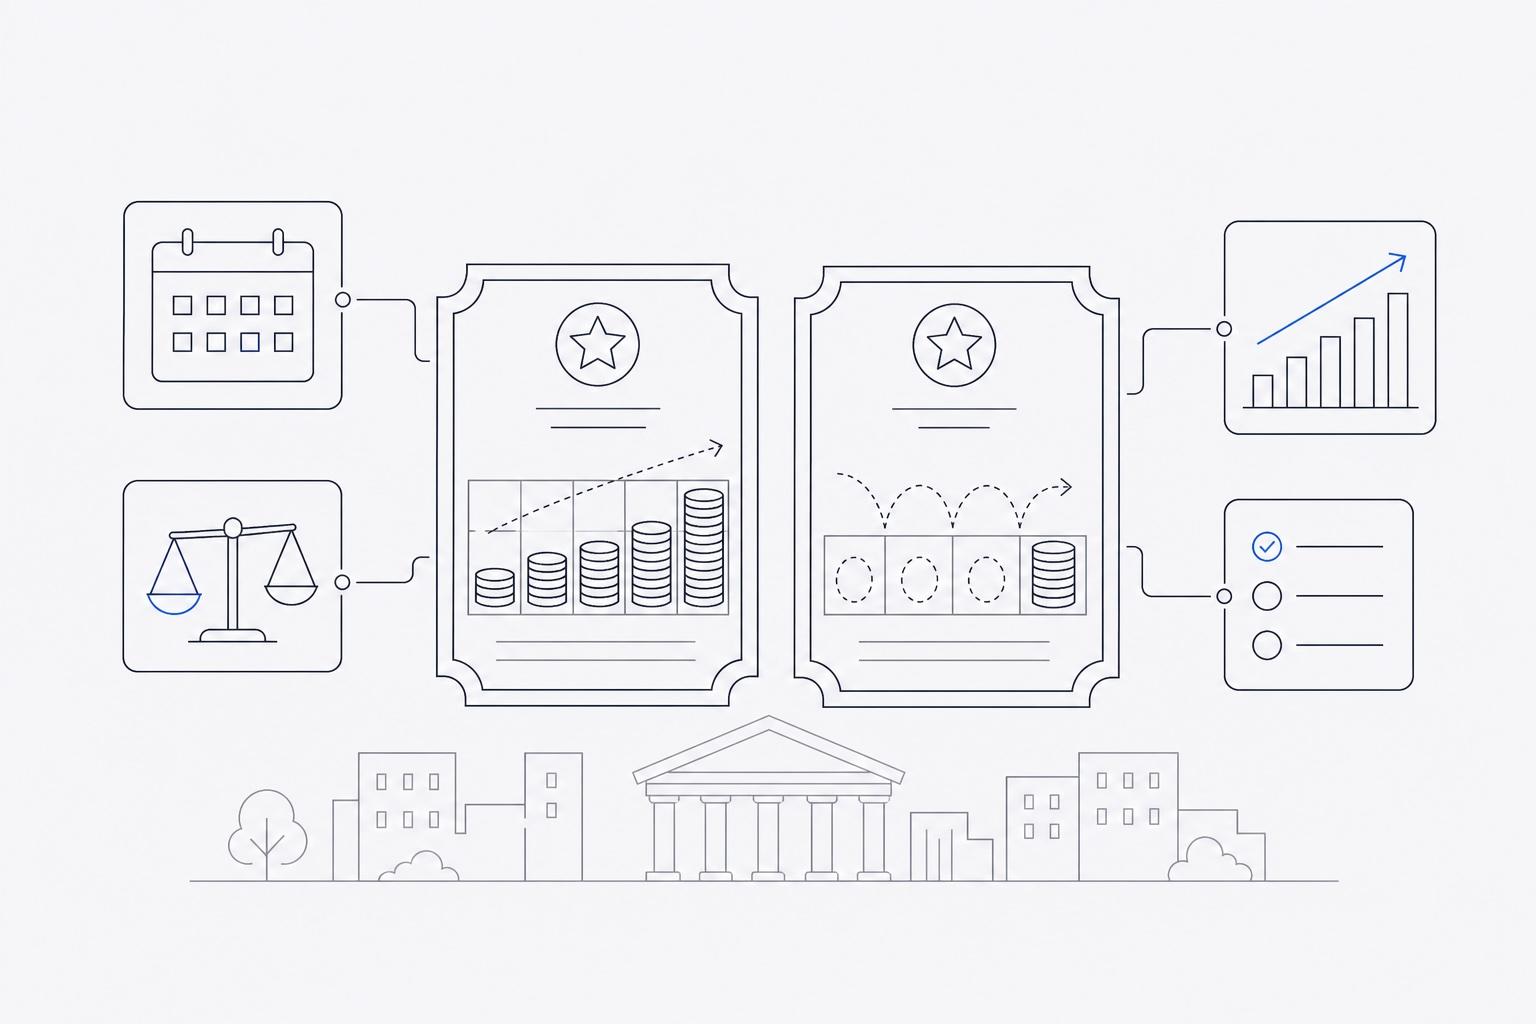
This guide explains cumulative preferred stock, non-cumulative preferred stock, and the practical gap between them. One clause in the prospectus decides whether a missed dividend can be paid later or is lost. It is cheap in calm markets and important when an issuer gets into trouble.
Every preferred stock prospectus says, often in language that is easy to miss, whether the dividend is cumulative or non-cumulative. For investors comparing cumulative vs non cumulative preferred shares, that clause can matter more than almost any other term.
What cumulative means
A cumulative preferred stock requires that any dividend the issuer skips keep building as an arrearage, the running total of missed payments. Before the company can resume paying common shareholders, and often before it can buy back common stock, it must first pay preferred holders every missed dividend in full.
That does not guarantee payment. A company in deep trouble may never have the cash to catch up. But the rule keeps pressure on management to restart payments. A board that answers to common shareholders cannot restore the common dividend until the arrearage is cleared. That gives the preferred holder a claim that looks more like a creditor's claim.
In past downturns, companies that suspended cumulative preferred dividends often paid the arrears later, sometimes years later. Holders of non-cumulative preferred stock have no such claim.
What non-cumulative means
A non-cumulative preferred stock offers no such protection. A company has skipped the dividend. The issuer has no duty to make it up, and shareholders have no legal claim to the missed payment even if the company later returns to profit.
The holder's main shield is the dividend stopper. It blocks common dividends or common stock buybacks while the preferred dividend is unpaid. That helps, because a company that skips the preferred dividend usually has to skip the common dividend too. But a warning is not a claim. In a crisis, boards have often cut both.
Why bank preferreds issued after 2013 are non-cumulative
Non-cumulative structures are common in bank and insurance preferred issues, and the reason is regulation, not marketing. The post-crisis capital rules say bank capital must absorb loss without forcing the bank to repay skipped amounts. A cumulative dividend creates a growing liability, so it works against that goal.
The United States adopted Basel III as the Regulatory Capital Rules, published by the Federal Reserve and the Office of the Comptroller of the Currency on October 11, 2013, with start dates of January 1, 2014 for the largest banks and January 1, 2015 for the rest. For a preferred stock to count as additional tier 1 capital, the layer just above common equity, the Federal Reserve rule at 12 CFR 217.20(c)(1) sets fourteen tests.
One of those tests says the bank must have full discretion at all times to cancel dividends or other payouts on the instrument, without causing a default or any other penalty other than a limit on common-share payouts. If a skipped dividend keeps building, it is not really cancelled. So a cumulative preferred stock cannot pass the test.
The agencies said that cumulative perpetual preferred securities generally would not qualify for additional tier 1 capital, and they chose not to include any cumulative instrument in tier 1 capital under the final rule.
That rule also ended the older route. Before 2013, bank holding companies could include trust preferred securities in tier 1 capital. These securities are cumulative and had limits on how much could be counted. The 2013 rule phased them out, so a bank that wants capital credit for a new preferred must issue a non-cumulative one.
Since then, almost all preferred stock issued by large banks has been non-cumulative. Cumulative structures remain common among real estate investment trusts, utilities, and industrial issuers, where no such rule applies. During the crisis, many financial firms suspended non-cumulative preferred dividends, and those missed payments were never made up.
A worked example: Hersha Hospitality Trust
Hersha Hospitality Trust, a hotel REIT, had three cumulative preferred share series outstanding in early 2020: a 6.875% Series C and two 6.50% series, D and E, each with a $25 liquidation preference.
On March 19, 2020, as its hotels emptied, the company revoked the dividends it had declared two weeks earlier on its common shares and on all three preferred series. The release, filed that day as an exhibit to Form 8-K, said unpaid preferred dividends would accrue without interest, and no cash dividend could be paid on the common shares until all accrued but unpaid preferred dividends had been declared and paid at the same time.
Four quarterly payments were missed: April 15, 2020; July 15, 2020; October 15, 2020; and January 15, 2021.
On March 9, 2021, the company said its board had declared the full arrearage: $1.7188 per Series C share and $1.625 per Series D and Series E share, payable March 26, 2021 to holders of record on March 19, 2021. The same release announced the next regular quarterly dividend. It is $0.4297 per Series C share and $0.40625 per Series D and E share. This is for the period ending April 15, 2021. The quarterly report for the period ended March 31, 2021 shows $24,172 thousand of dividends paid on preferred shares in that quarter.
The figures line up. Four quarters at $0.4297 equals $1.7188 on Series C, and four quarters at $0.40625 equals $1.625 on Series D and E. Across the shares outstanding at March 31, 2021, the catch-up came to about $24.2 million.
Hersha Hospitality Trust, arrears paid March 26, 2021. Form 8-K exhibit of March 19, 2020; press release of March 9, 2021; Form 10-Q for the quarter ended March 31, 2021.
Holders waited a year and got no interest for the delay. They still got every dollar, because the charter required payment before a common dividend could be paid. Had the three series been non-cumulative, the same 12 months would have produced nothing. In 2023, someone took Hersha private and redeemed its preferred shares, so the series no longer appears on YieldDesk, but the filings remain on EDGAR.
Where the two structures live
Of the 534 preferred stocks on YieldDesk as of November 9, 2026, 347 are cumulative and 187 are not. Every one of the 136 real estate preferreds is cumulative, as is every one of the 64 utility preferreds. In the financial sector, 183 of 249 issues are non-cumulative. That label groups banks with insurers, closed-end funds and finance companies, and the cumulative issues in it include fund-issued preferreds and trust certificates that sit outside bank capital.
How YieldDesk marks cumulative status
The designation is a standard field on every preferred record and comes from the prospectus. On the record page, it shows as a chip beside the ticker, in the same row as the exchange and sector: Cumulative in green or Non-cumulative in grey.
Baby bonds carry no chip, because bond interest is debt, not a dividend.
In the Preferreds screener, Cumulative is a yes-or-no filter, so a reader can limit a screen to one structure or the other. The Risk view adds a Non-cumulative flag on the row, with the hint that a skipped dividend does not accrue and need not be made up. That flag is a description, not a judgment.
The Securities search box accepts cumulative as a token, so yield>7 cumulative returns only issues with the make-good promise. The Income Quality Score methodology treats structure as one of its measures and reads a non-cumulative bank preferred as the regulatory standard, not as a defect, while a non-cumulative issue outside the financial sector is flagged for review.
Baby bonds and trust preferreds
The distinction works differently for the two instruments that trade beside preferreds on the exchange.
Baby bonds
A baby bond is a bond issued in $25 units. Its coupon is interest, not a dividend, and the issuer has no discretion over it. A missed payment, once any grace period runs out, is a default that gives bondholders the remedies of creditors. Cumulative and non-cumulative do not apply. The protection is stronger than either. Someone owes the payment, and the claim ranks ahead of every class of preferred stock.
Trust preferreds
A trust preferred security sits in between. A trust sells preferred securities to the public and uses the proceeds to buy junior debt from the parent company, usually a bank, then passes the interest through as distributions. The parent may defer that interest, usually for up to five years, and deferred interest keeps accruing, so the distributions are cumulative in effect.
That is why the 2013 capital rule removed trust preferreds from tier 1 capital and why few have been issued since. YieldDesk displays survivors such as Citigroup Capital XIII (C-N), which matures in 2040, as cumulative, and their distributions count as interest for tax purposes, not qualified dividends.
Finding the clause and weighing it
The cover page and the description of securities section of the prospectus usually state the structure plainly, often in the security's own name. The yield gap between similar cumulative and non-cumulative issues is often only a fraction of a point, so the two can look alike. In calm markets, the difference can seem remote.
For investors comparing cumulative vs non cumulative preferred shares, the real difference shows up after a suspension. That matters most for cyclical businesses, where a dividend pause is a real risk. For bank issuers, where the non-cumulative structure is required, the analysis shifts to capital strength and dividend history, because the structure gives no claim on missed dividends.
If the payment stops, the holder of a cumulative preferred has a growing claim. The holder of a non-cumulative preferred has none.
Q&A
Question: Does cumulative preferred stock guarantee that missed dividends will be paid later?
Short answer: No. Cumulative status means missed dividends build as arrears and usually must be paid before common dividends or common stock buybacks can resume. It does not guarantee recovery if the issuer never regains the cash to pay.
Question: Why are most post-2013 bank preferred stocks non-cumulative?
Short answer: Bank preferreds are usually non-cumulative because of capital rules, not because banks prefer the structure for business reasons. To count as additional tier 1 capital, a bank preferred must let the bank cancel dividends without creating a liability or default. A cumulative dividend keeps growing when skipped, so it does not meet that standard.
Question: What practical lesson does the Hersha Hospitality Trust example show?
Short answer: Hersha shows the value of cumulative wording during stress. The company skipped four quarterly preferred dividends in 2020, but because the preferred shares were cumulative, the missed payments built up. In 2021, Hersha paid the full arrearage before it restored regular preferred payments. If the same preferreds had been non-cumulative, holders would not have had a contractual claim.
Question: Is a non-cumulative preferred always a bad security?
Short answer: Not always. In banks, non-cumulative preferred stock is the regulatory standard, so the focus should be on capital strength, earnings, and dividend history. Outside financial issuers, though, a non-cumulative structure deserves closer review because many real estate, utility, and industrial preferreds are cumulative, and the lack of accrual can leave holders with no recovery after a skipped dividend.
Question: How do baby bonds differ from cumulative and non-cumulative preferred stocks?
Short answer: Baby bonds are debt, so their payments are interest, not dividends. If an issuer misses interest and any grace period expires, that is a default and bondholders have creditor remedies. Cumulative and non-cumulative labels do not apply to baby bonds because the issuer does not have the same freedom to skip payments that it may have with preferred dividends.
Library articles are general information about securities and markets. They are not advice on any security or on whether to buy or sell it. Disclosures
The preferred stocks list shows every public record with its price, coupon, call date and yield.
The preferred stocks listRelated articles
How to Tell if a Preferred Stock Will Be Called or Redeemed
YieldDesk · 7 min
Covered-call ETFs: income or principal
Manish Hemrajani · 8 min
Understanding the Basics of Business Development Companies (BDCs)
Manish Hemrajani · 6 minOne issue, every Sunday.
Eight blocks of data, one chart, no commentary. Rates, the week's movers, listings and filings across preferred stocks, BDCs and covered-call ETFs.
Free · Sundays · unsubscribe at any time · addresses are never shared