Credit Ratings for Preferred Stocks: How Notching Works
Credit ratings for preferred stocks usually sit one to three notches below senior debt. See how notching, split ratings and unrated preferreds work.
Manish Hemrajani7 min readPublished Updated
How do rating agencies notch preferred stock?
What widens or narrows the notching gap?
Why are bank preferreds rated lower?
What does an unrated preferred stock mean?
What are split ratings?
Do ratings keep up with the market?
How should income investors use preferred stock ratings?
Frequently asked questions
How many notches below senior debt is preferred stock rated?
Why can the same company have different ratings on its bonds and preferred stock?
Is an unrated preferred stock riskier?
What is equity credit?
Do ratings change before the market reacts?
Takeaways for income investors
Credit rating agencies usually rate preferred stock one to three notches below the issuer's senior unsecured debt. The gap reflects two things: preferred stock sits lower in the capital structure, and its dividends are discretionary. The same company, with the same business risk, can carry an A- rating on its bonds and a BBB or lower rating on its preferred shares.
Meta description: Credit ratings for preferred stocks sit one to three notches below senior debt. Learn how notching, split ratings and unrated preferreds work.
By the YieldDesk research team. Read time: 6 minutes.
How do rating agencies notch preferred stock?
Agencies do not judge preferred stock the way they judge senior debt from the same issuer. For this asset class, that difference matters more than it does almost anywhere else in fixed income.
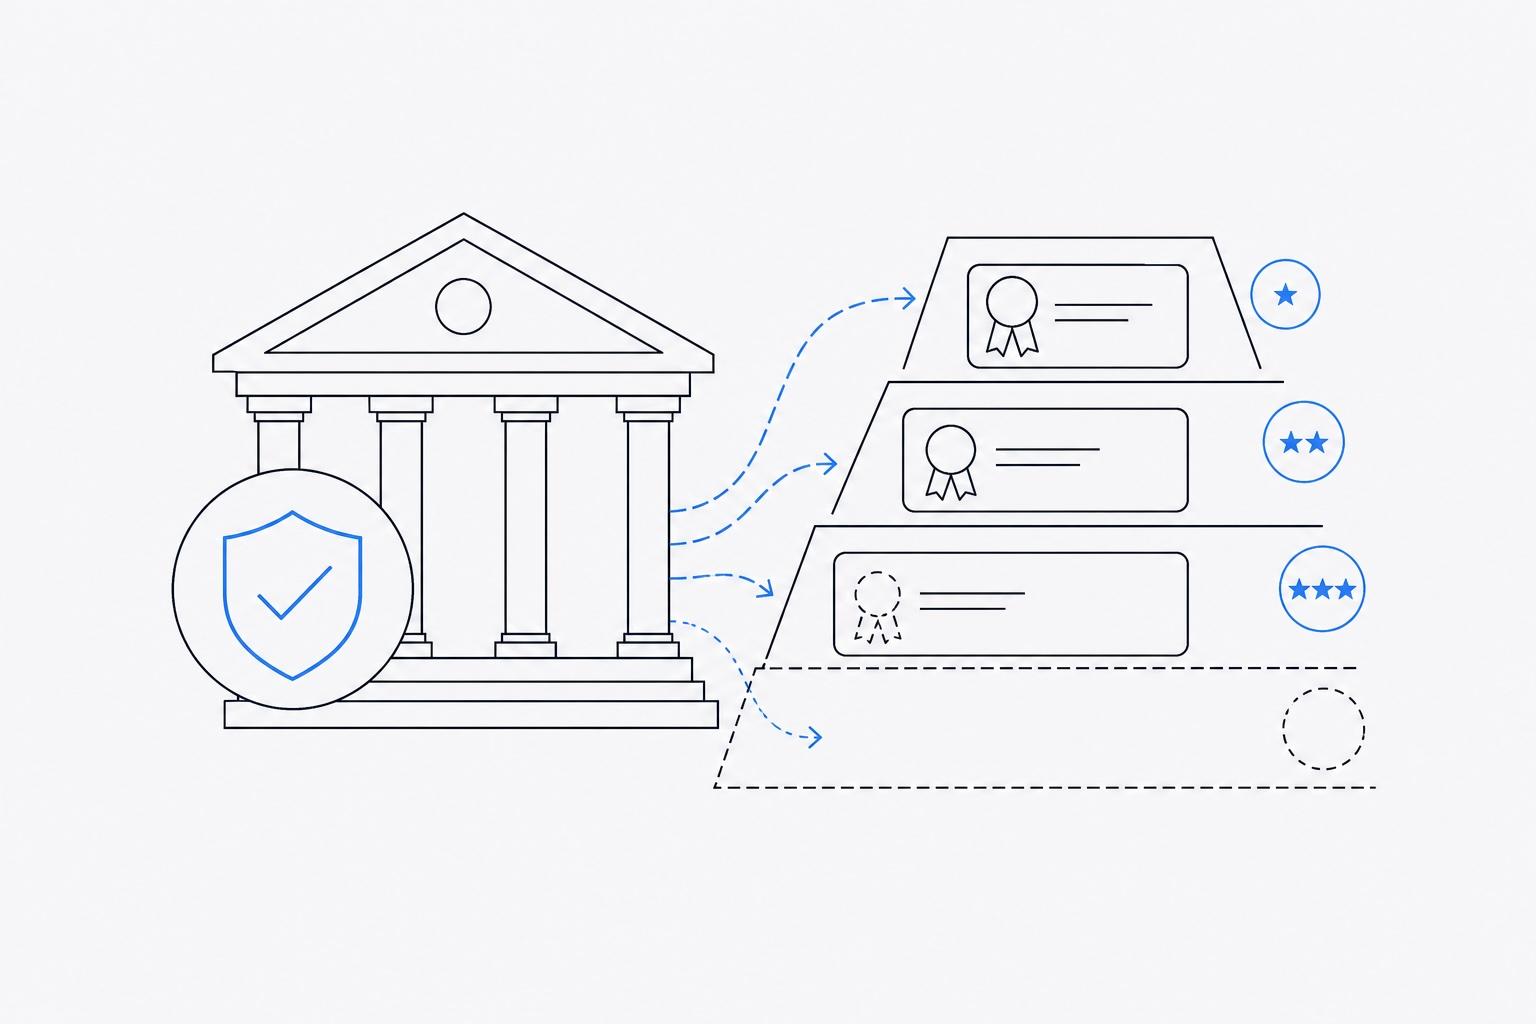
Moody's, S&P Global Ratings and Fitch each apply notching to subordinated securities. Notching means rating a security a set number of steps below the issuer's senior unsecured debt rating. A company rated A- on its senior debt might see its preferred stock rated BBB or lower, even though both securities come from the same entity.
The gap is not an inconsistency. It is the methodology working as designed. It prices the difference in expected loss between two claims on one enterprise.
What widens or narrows the notching gap?
The width of the gap varies in a systematic way. For investment-grade industrial issuers, two notches below the senior rating is a common convention. Agencies often widen the gap for issuers with elevated leverage or a rating below investment grade. Their reasoning is that the probability of a dividend deferral rises disproportionately as overall credit quality declines.
Structural features matter too. Non-cumulative dividends, deep subordination and provisions that allow deferral without consequence all argue for wider notching. Agencies weigh how likely it is that a payment could be skipped without the broader consequences a missed bond payment would carry.
Factor | Tends to widen the gap | Tends to narrow the gap |
|---|---|---|
Issuer credit quality | Elevated leverage or a rating below investment grade | Investment-grade industrial issuer |
Dividend terms | Non-cumulative dividends; deferral allowed without consequence | Terms that make a skipped payment costly |
Capital structure position | Deep subordination | Less severe subordination |
Source: general agency methodology as described above. Individual agency criteria differ.
Why are bank preferreds rated lower?
Financial institutions add another layer. Banks issue preferred stock structured to qualify as regulatory capital, and regulators insist that these structures absorb losses while the institution keeps operating.
Agencies apply extra scrutiny, and extra notches, to those loss-absorption features. That is why the preferred stock of even the largest and most familiar banks frequently carries a rating at the lowest rung of investment grade or below it.
One related point: agencies often give hybrid securities partial "equity credit" when assessing the issuer's own leverage. For the issuer's rating, the preferred counts as part debt and part equity. The agencies still rate the security itself several notches down. The two treatments do not conflict, because they answer different questions. One asks how leveraged the company is. The other asks how likely this particular payment is to be made.
What does an unrated preferred stock mean?
A substantial portion of the exchange-traded market has no rating at all. Many baby bonds and preferreds from smaller issuers, business development companies and specialty finance firms are unrated. Poor credit is not necessarily the reason. The issuer may simply have declined to pay for coverage of a retail-oriented issue.
An unrated security needs independent analysis. It neither deserves the benefit of the doubt nor warrants automatic exclusion. Without an agency opinion, the work shifts to the filings: earnings coverage, leverage and the terms of the security itself.
What are split ratings?
A split rating occurs when two agencies disagree by a notch or more on the same security. Splits are common in the preferred market. They often mark securities where reasonable analysts differ, and that disagreement can be a source of value for investors willing to do the work.
A split does not mean either agency got it wrong. It is a prompt to read the reasoning. Find out which factors each agency weighted differently, such as the loss-absorption features, the leverage or the dividend terms.
Do ratings keep up with the market?
Ratings move slowly by design, and the market often reprices a security well before an agency acts. A preferred trading at a yield far wider than its rating category suggests is telling you something. The task is to decide whether the market or the agency has the better argument.
Downgrades from investment grade to below investment grade can also create dislocations. Rating-constrained funds are forced to sell, and prices can fall sharply. Historically, these episodes have been among the more fertile hunting grounds for patient buyers. A lower price alone does not make a security safe, though. Dividend deferral risk and call risk still apply.
How should income investors use preferred stock ratings?
For an income investor, the practical implications come down to three points.
Do not apply the issuer's senior rating to its preferred stock without adjustment. The security's own rating, where one exists, is the relevant figure.
Read the rating alongside the measures that drive it. These include earnings coverage of fixed charges, leverage and, for financial issuers, regulatory capital ratios.
Treat ratings as an input, not a verdict. A rating compresses a committee's judgment into a letter grade. The grade leaves out the security-specific provisions, call structures and market technicals that often matter as much as the credit itself.
Call structure is one of those omitted provisions. A preferred can look attractive on current yield and still deliver much less if it is redeemed at par. Our guide on how to tell if a preferred stock will be called or redeemed covers that side of the analysis. YieldDesk's screeners and alerts let you filter more than 950 preferred stocks, preferred ETFs, covered-call ETFs and BDCs and track call windows and distributions.
Frequently asked questions
How many notches below senior debt is preferred stock rated?
Preferred stock is typically rated one to three notches below the issuer's senior unsecured debt. For investment-grade industrial issuers, two notches is a common convention. The gap is often wider for highly leveraged issuers or those rated below investment grade.
Why can the same company have different ratings on its bonds and preferred stock?
The two securities carry different claims on the same enterprise. Preferred stock ranks lower in the capital structure, and its dividends are discretionary. Notching prices the difference in expected loss between the two.
Is an unrated preferred stock riskier?
Not necessarily. Many baby bonds and preferreds go unrated because the issuer declined to pay for coverage, not because the credit is poor. An unrated security needs independent analysis of the issuer's filings and the security's terms.
What is equity credit?
Equity credit is the share of a hybrid security that an agency treats as equity when assessing the issuer's own leverage. The preferred is counted as part debt and part equity for the issuer's rating, while the security itself is still rated several notches below senior debt.
Do ratings change before the market reacts?
Usually the market moves first. Ratings change slowly by design, so a yield far wider than the rating suggests may be telling you something the agency has not yet reflected.
Takeaways for income investors
Use the preferred's own rating, not the issuer's senior rating, and adjust for notching when only the senior rating exists.
Read the rating alongside earnings coverage of fixed charges, leverage and, for financial issuers, regulatory capital ratios.
Treat a letter grade as one input. Call provisions, deferral terms and market pricing often matter as much as the credit.
Learn more at yielddesk.co.
This article is research, not investment advice. Preferred stock dividends can be deferred or cut, and securities can be called or lose value. Verify any figure against the issuer's filings before you act.
Library articles are general information about securities and markets. They are not advice on any security or on whether to buy or sell it. Disclosures
The preferred stocks list shows every public record with its price, coupon, call date and yield.
The preferred stocks listRelated articles
Is the JEPI distribution return of capital
Manish Hemrajani · 8 min
Snowball Analytics Alternative: 6 Tools Compared for 2026
YieldDesk · 8 min
Seeking Alpha Alternatives for Preferred Stock and High-Yield Income Investing (2026)
YieldDesk · 8 minOne issue, every Sunday.
Eight blocks of data, one chart, no commentary. Rates, the week's movers, listings and filings across preferred stocks, BDCs and covered-call ETFs.
Free · Sundays · unsubscribe at any time · addresses are never shared